Brief takeaways:
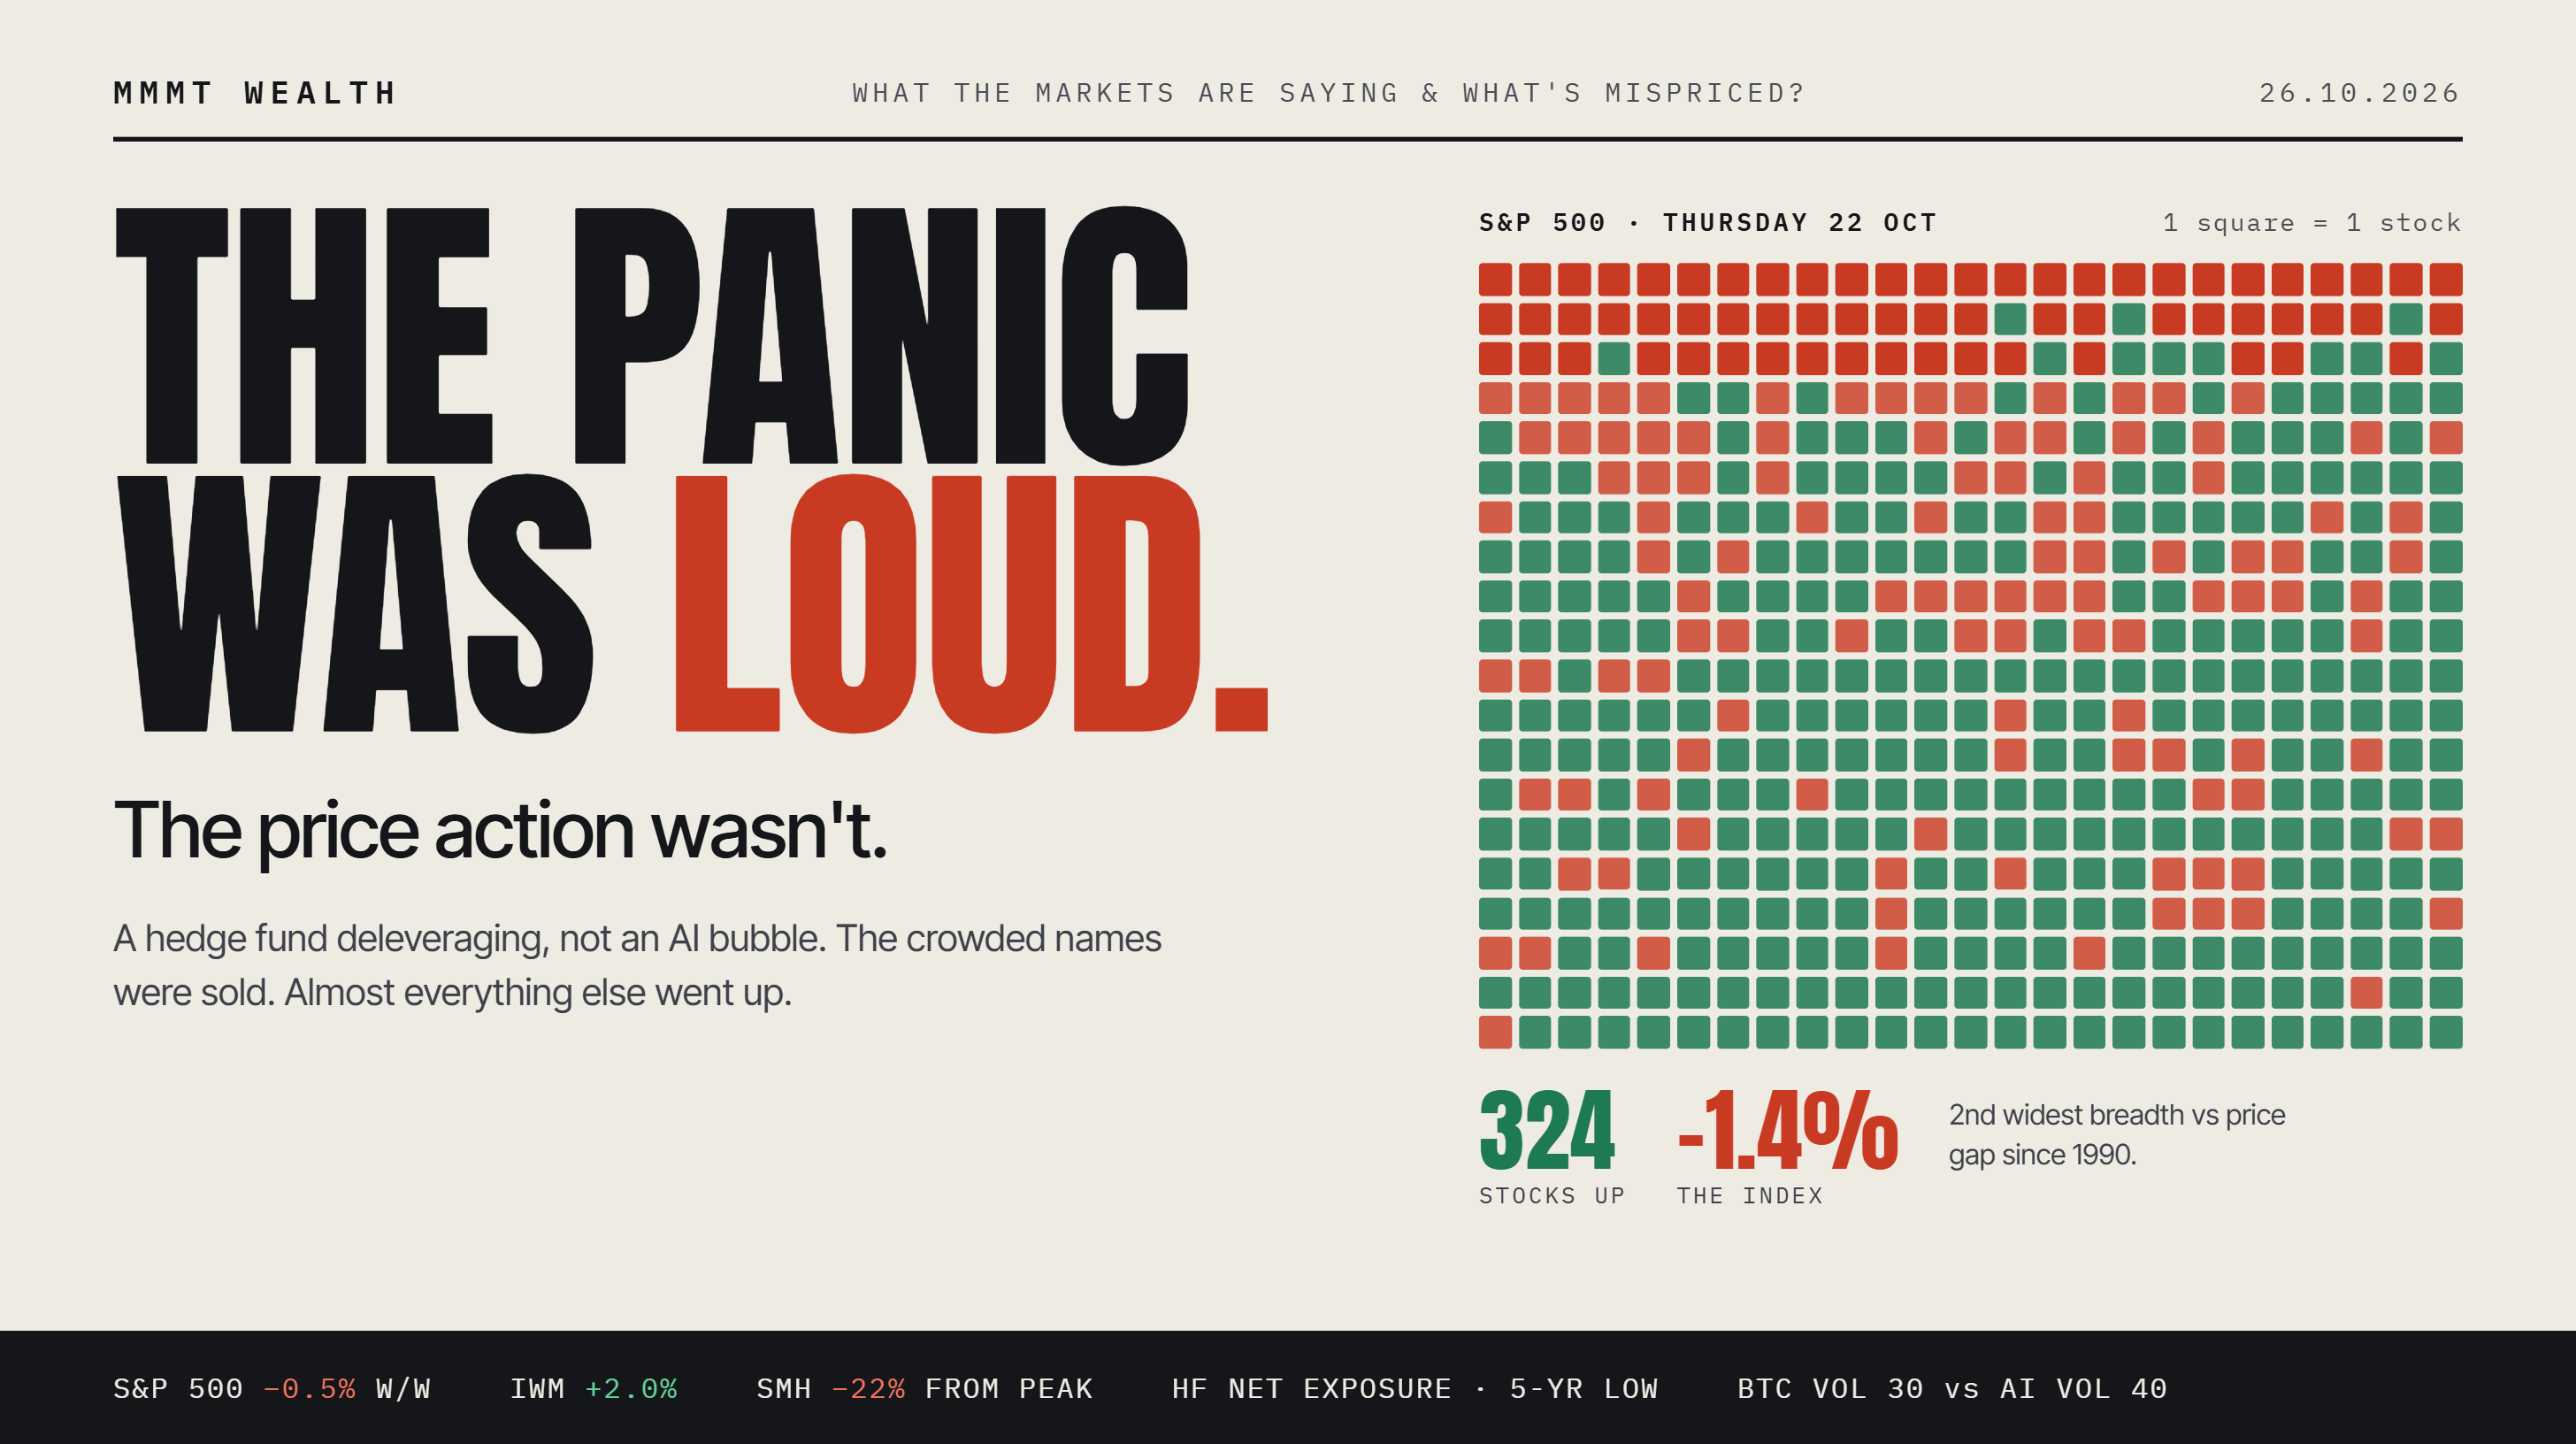
This isn’t an AI bubble bursting. It’s a continued hedge fund deleveraging event that we are nearing the end of. The S&P 500 fell only 0.5% over the last week.
Economically we remain fine still. Profits continue to grow, margins continue to grow, jobless claims isn’t up as much as the media wants us to believe, demand still remains through the roof.
Listen to the companies and not the media or research notes. Lumentum is sold out through to 2029, ASML sees shortages to 2028, and Marvell is targeting a 10x in revenue by 2031. That’s not what a demand problem looks like.
There’s no bubbles in valuations either. Earnings are growing faster than prices and multiples are shrinking (NVDA is at ~15x Fwd PE). We’re only 2-3 years into a decade long buildout.
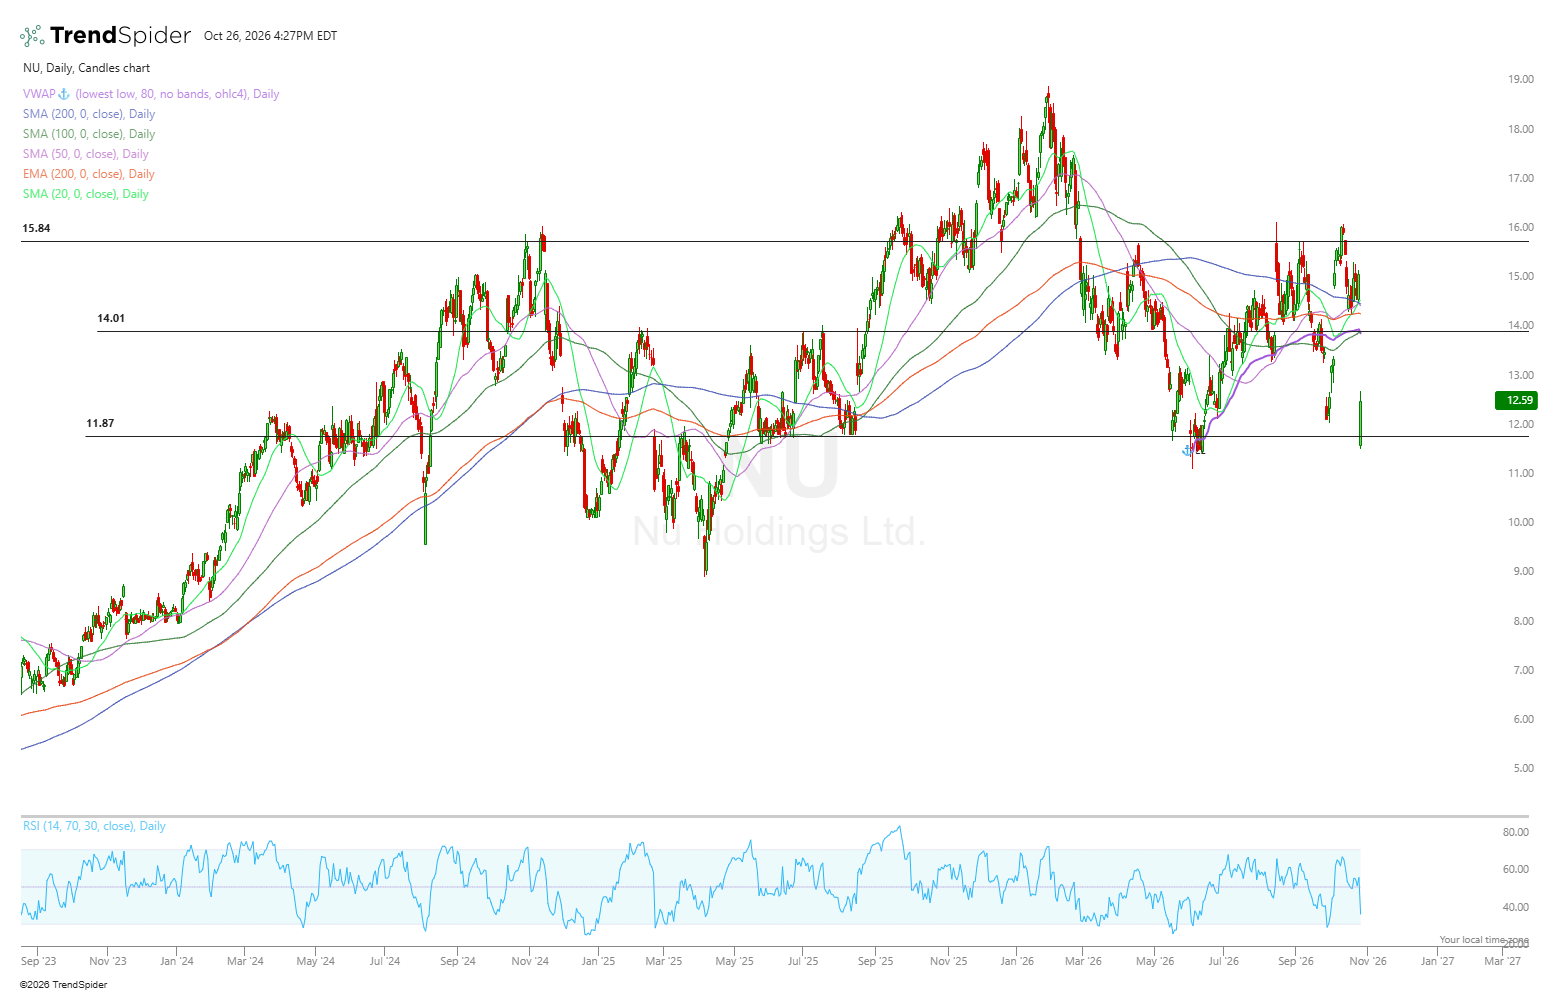
Brazil’s iShares MSCI ETF (ETF) sold off 21% post a Lula Da Silva surprise win. Markets were clearly all in on the other side and overshot. NU fell ~20% despite its first $1B profit quarter. That’s an overreaction though I still recommend caution.
November 1st Web-App Release
On November 1st I’m releasing my web-app to all subscribers (paid will have far more use).
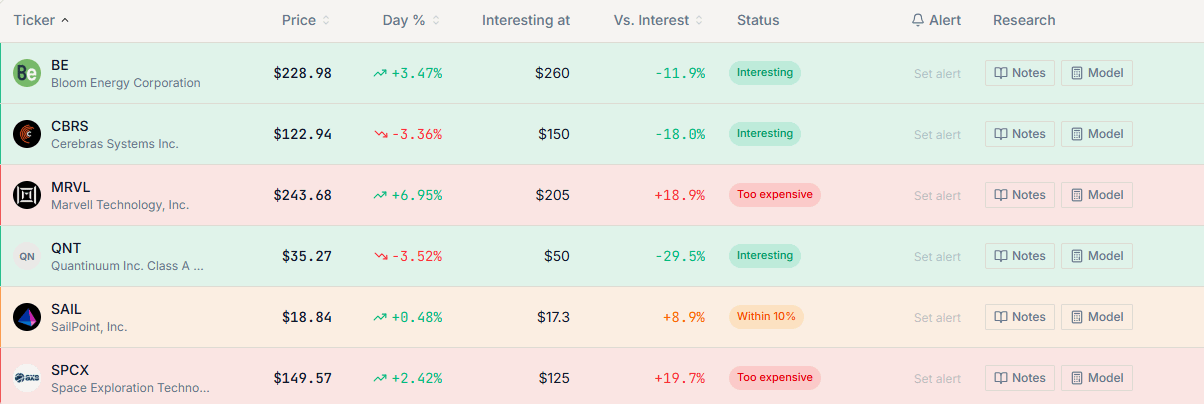
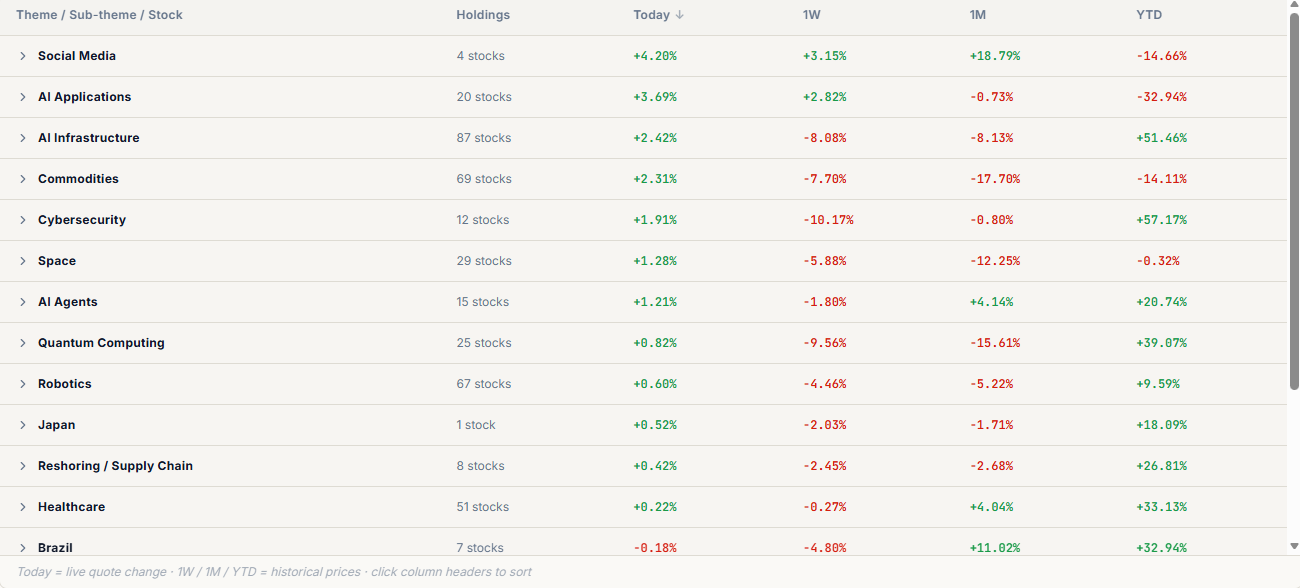
Here are a few snips and teasers from the site:
Model your own stocks or just follow my models.
Create your own watchlist.
Track investment themes and the AI supply chain.
Track all my daily notes and my stance on individual companies.
Track my valuations.
The panic was loud again this week but the price action told a completely different story.
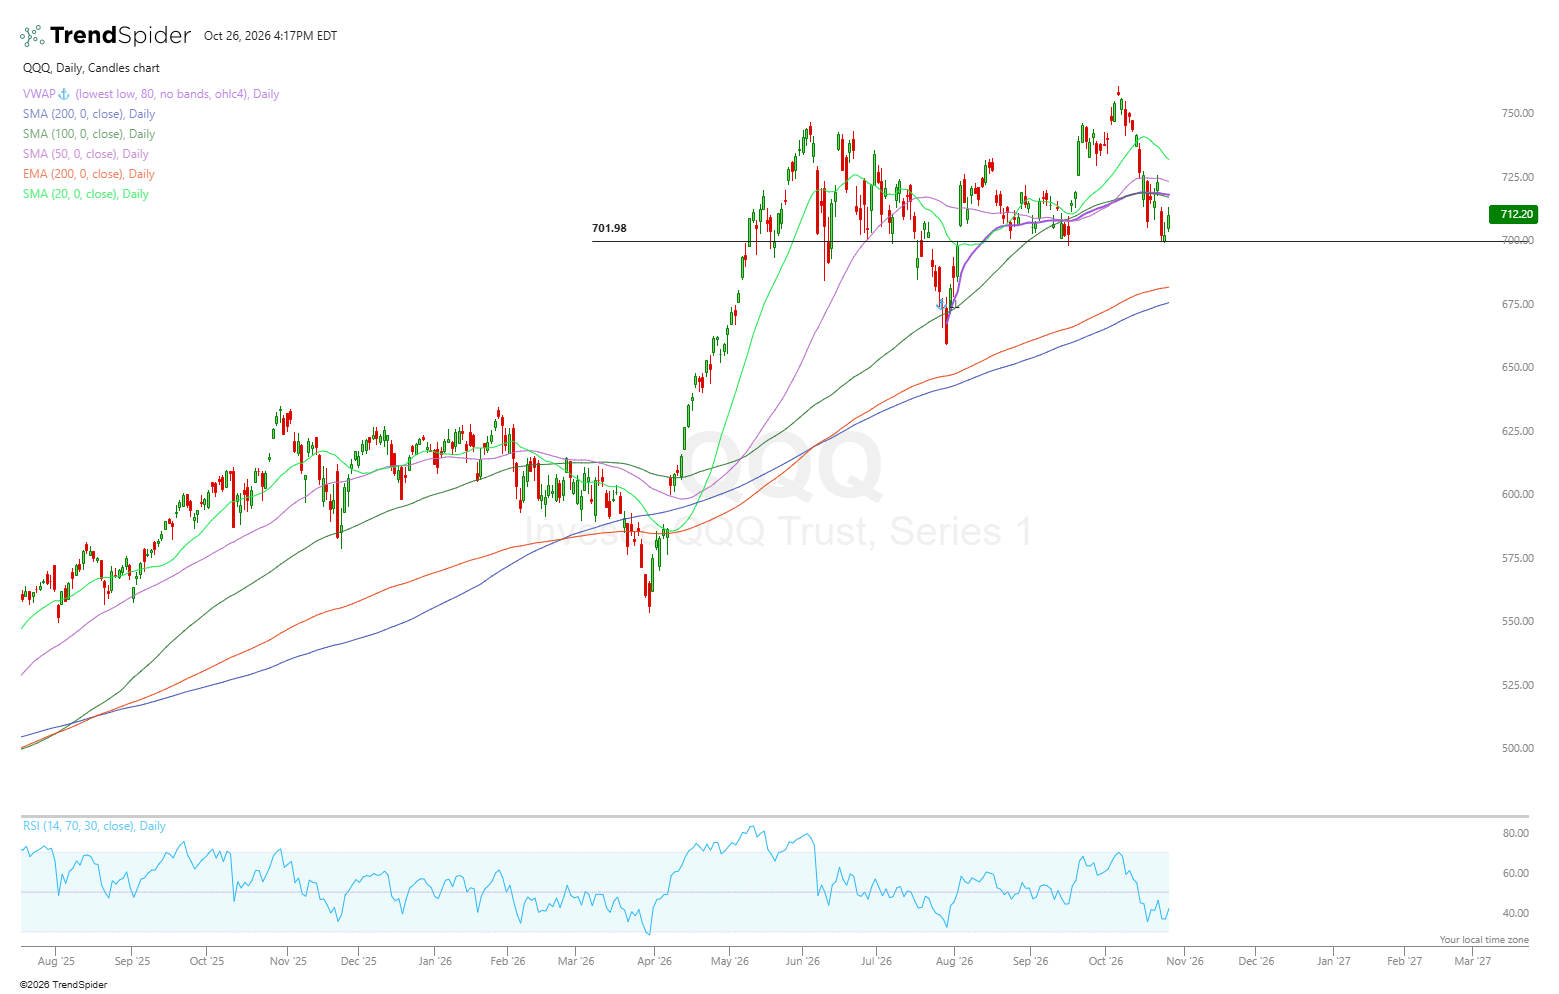
Last week I titled my weekly article “More FUD. Less Logic”. I said the AI bubble didn’t pop…but hedge fund deleveraging caused the sell off. This last week just gave us more evidence of that.

By lack of logic last week here’s what I mean:
Tokenized stocks got hammered over the weekend…Hence retail investors called for a “Black Monday”…Then a small neocloud’s IPO in Australia fell apart…And then the FT and the rest of the media ran a story on whether the returns on AI will pay for itself.
But look at what actually happened:
The SPY fell 0.5% for the week.
The QQQ fell less than 1% last week and is now up 0.5% over the 5 trading days (at the time of writing this on Monday morning).
iShares Russel 2000 (IWM) / Small caps (the most rate sensitive parts of the market) are up 2.3% over the last week.
That’s the “collapse” narrative the media are trying to paint. This is why I continue to believe we’re in the very late innings of this AI infrastructure sell off.
Here’s some more evidence backing up why we’re in the late innings:
Thursday was the day we saw the QQQ fall ~3%, yet over 60% of the SPY names on that day finished in the green. What does that say?
It says that the economy is not being sold…but that a small group of crowded names are being sold by the same people at the same time.
And then listen to those at the centre of the AI buildout (rather than FT journalists for example):
SpaceX (SPCX) said that compute demand is substantially greater than supply and they could rent out compute several times over.
Nebius (NBIS) has raised prices twice in three months. In May it lifted on-demand GPU prices by an average of ~29%. Then in October it raised them again by another 17% all because demand for compute is outstripping supply. As a reminder, companies in a bubble cut prices to fill capacity. The opposite is happening.
And finally we have GPU rental prices sitting far ahead of standard 6-year depreciation schedules.
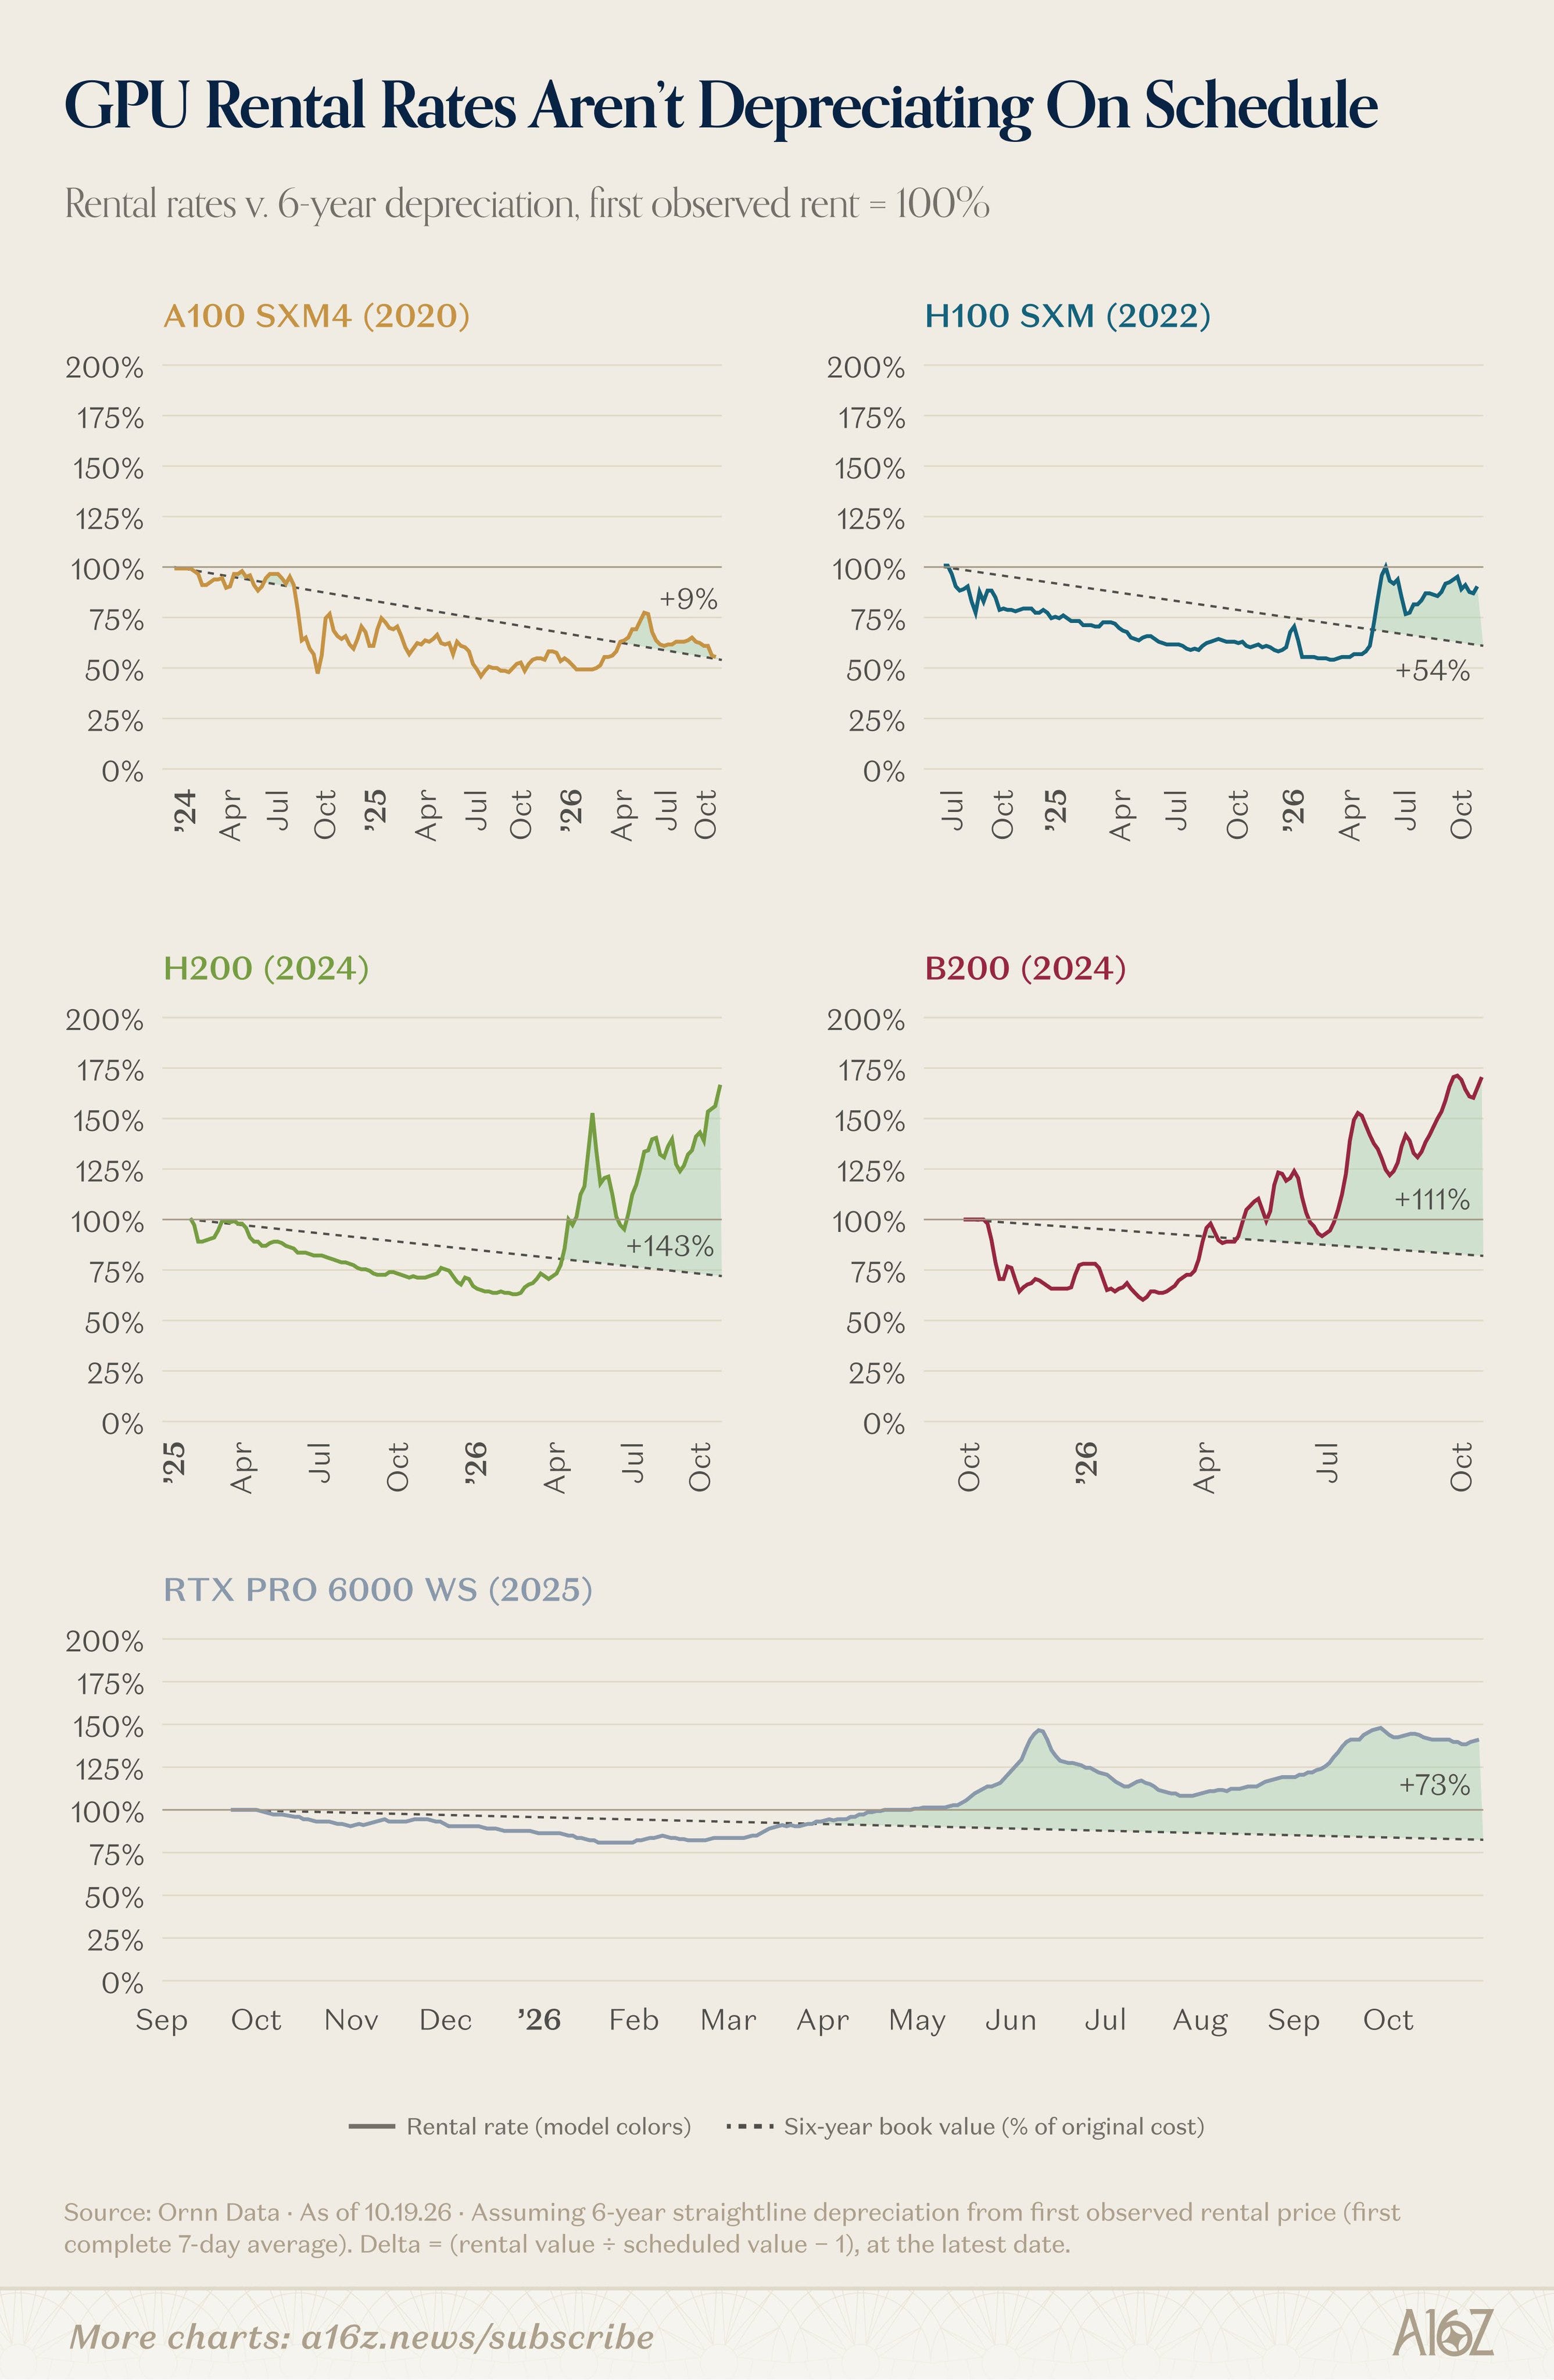
To put it simply…until we have one company in this cycle tell us demand is slowing, I don’t believe the risks outweigh the rewards at all. There is potential hedge fund deleveraging may set us back another 5-10% but the upside of the AI trade is still tenfold the downside risk.
We remain in year 2-3 of a 10+ year buildout and people are calling for “bubble.”
Is Hedge Fund Deleveraging Finished?
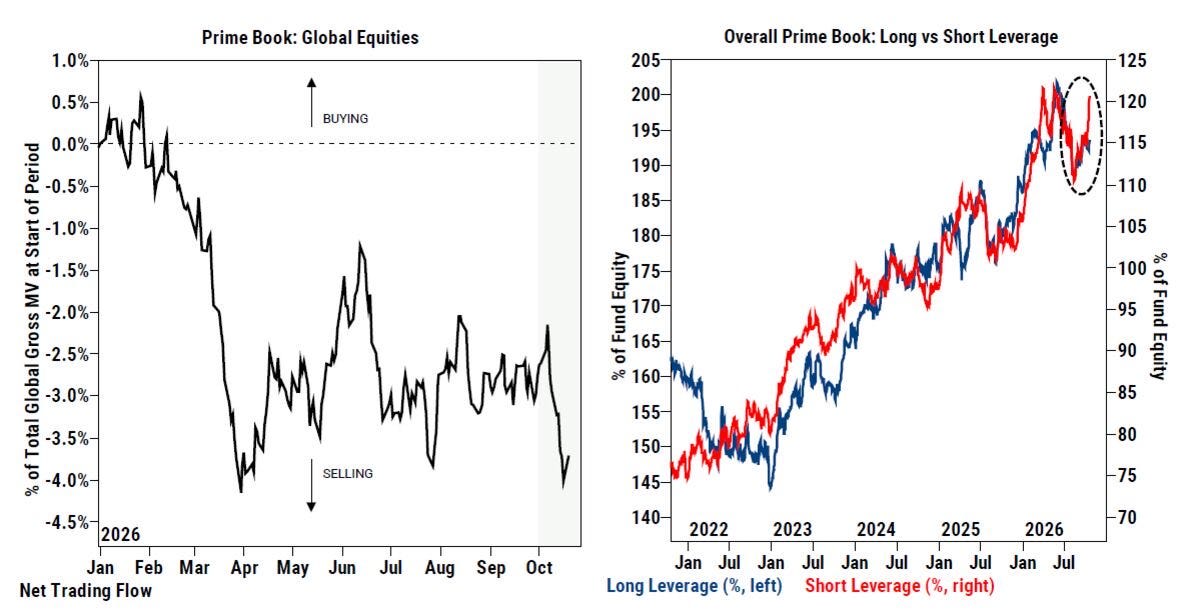
This is a very tough question to answer… especially compared to the “are we in a bubble?” question which is easy to answer.
Let’s walk through the logic:
Hedge fund net selling of AI stocks has now fully reversed a lot of gains since May / June 2025. This is suggestive of a huge amount of risk coming off the table all at once. Goldman Sachs reported that this is the second largest net selling of global AI stocks in the past year and hedge fund net exposure has not been this low (aside from Liberation Day) in the last five years. At these kinds of numbers, there’s simply not much left to sell. Once hedge funds have cut their exposure, the forced selling pressure dries up and price movements revert back to being set by what they should be set by…fundamentals.
November is approaching. This sounds trivial but it matters a lot as funds are judged month to month by investors. Each month is a “reset” so once a new month starts, a hedge fund can start adding risk again.
Selling last week happened across the entire board…not just in the equity markets. This is a very important distinction because it’s suggestive that hedge funds were almost selling whatever they could…rather than just the AI trade, or just equities. When selling pressure starts hitting much more than just equities…this tends to mean we’re in the late innings rather than the early innings of the deleveraging.
None of this is to say we’re done with the selling pressure. Saying that here would be naive…but I feel much more confident suggesting we’re in the later innings rather than the early innings here.
Macro Update
S&P now trades at 18.7x forward earnings which is below its five year average of 19.8x. Meanwhile Q3 earnings are growing +29% with the vast majority of companies beating earnings so far (and likely many more to come). Earnings continue to outrun valuations. Not the other way around.
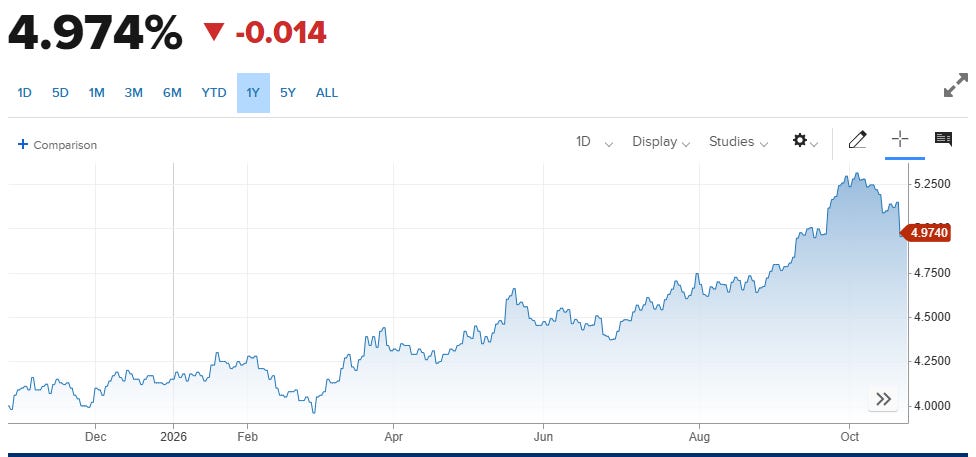
The 10-year yield is now sub 5% which is still heightened but on the way down from +5.2% we saw at the start of October. As I’ve said the entire sell off, an investment boom raises the neutral rate. High yields alone aren’t a reason to be bearish on AI, but they will keep pressure on housing and small caps.
AI capital is only just starting to hit the credit markets. Free cash flow has been mostly been used until now by the hyperscalers and it’s only now we’re seeing financing. Again, this is more evidence that this is extremely early on in the buildout.
Junk spreads have hit an all-time tights which is a sign worth watching for the bears. Just one sign amidst many but alone it is not a bearish indicator.
Brazil: An Overreaction But Worth Being Cautious
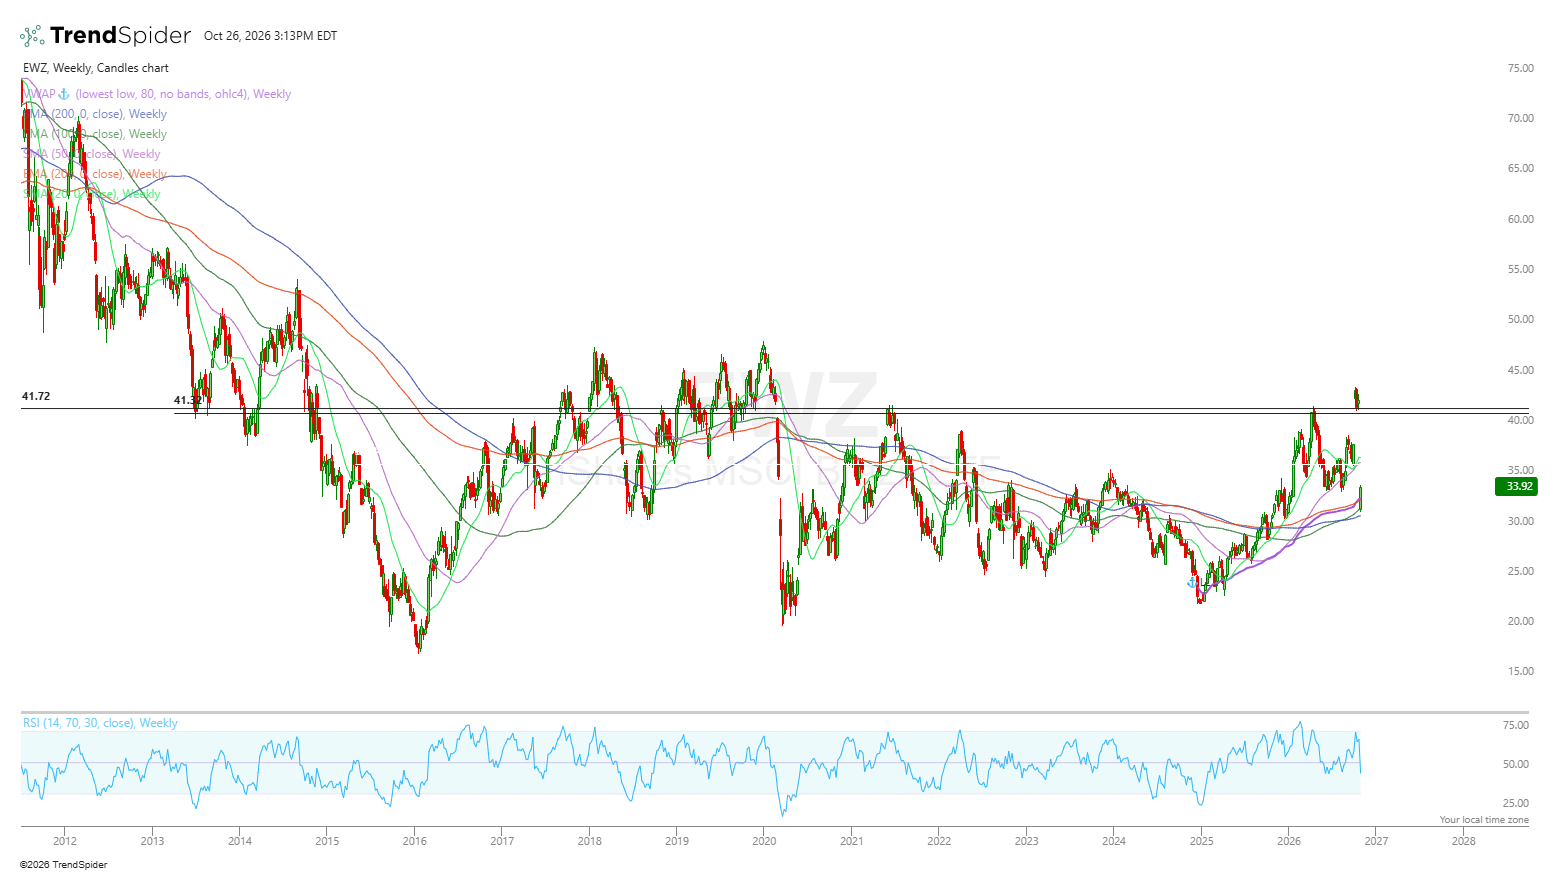
Brazil had its own deleveraging event today but just with a political trigger.
Lula won Sunday’s runoff 51.8% to 48.2%. Markets had been all-in Bolsonaro after he took the first round of votes and prediction markets had a Bolsonaro win at ~80% on the day of the vote.
So when the results came in the Brazilian Real fell ~10% and EWZ fell ~21%.
For context, between the first round of results and Friday, EWZ rallied only 7% so today’s move didn’t just give that back… it went well past it.
That’s the same pattern as the AI trade we’ve seen. One crowded bet with everyone on the same side and nobody to sell to when it goes wrong. This makes it more of a positioning reset that can be taken advantage of rather than a sudden collapse in the Brazilian economy.
Some points worth noting on Brazil right now:
Lula will be constrained and anything remotely radical will be very hard to push through.
There is likelihood of political unrest. No major protests have been reported yet but observers warn any refusal post Bolsonaro’s request for annulment could trigger them. This is why the near term could continue to get worse for Brazil but this is something to monitor.
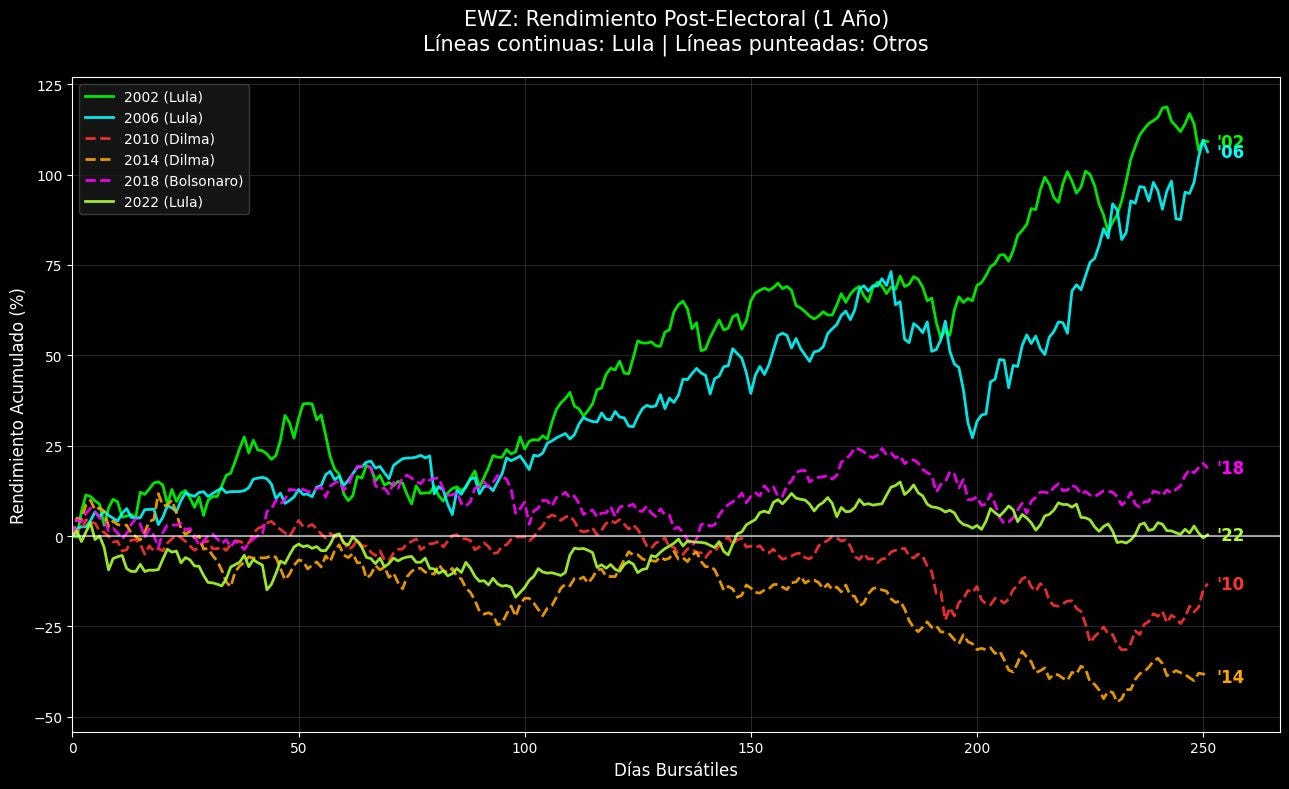
But finally on a more positive note… let me leave you with this chart below for returns under Lula since 2002.
It may not be all that bad for the stock market.
Commodities
We remain bullish on silver, copper, solar, and scandium.
No change in view this week. The structural case hasn’t changed:
Silver is still in its fifth straight year of structural deficit with ~80% mined as a by-product so supply can’t respond quick enough. With AI’s push for efficiency (cost per token), silvers conductivity is extremely valuable.
Copper is needed for every GW of data centre capacity, every grid upgrade and every on-site power plant. And with the grid struggling to keep up, the buildout needs more of all three, so copper demand only rises from here.
Solar still remains a key play of mine on the power bottleneck and solar being one of the fastest and cheapest sources to build and permit.
Crypto
Bitcoin has continued to hold firm again whilst the AI trade struggled.
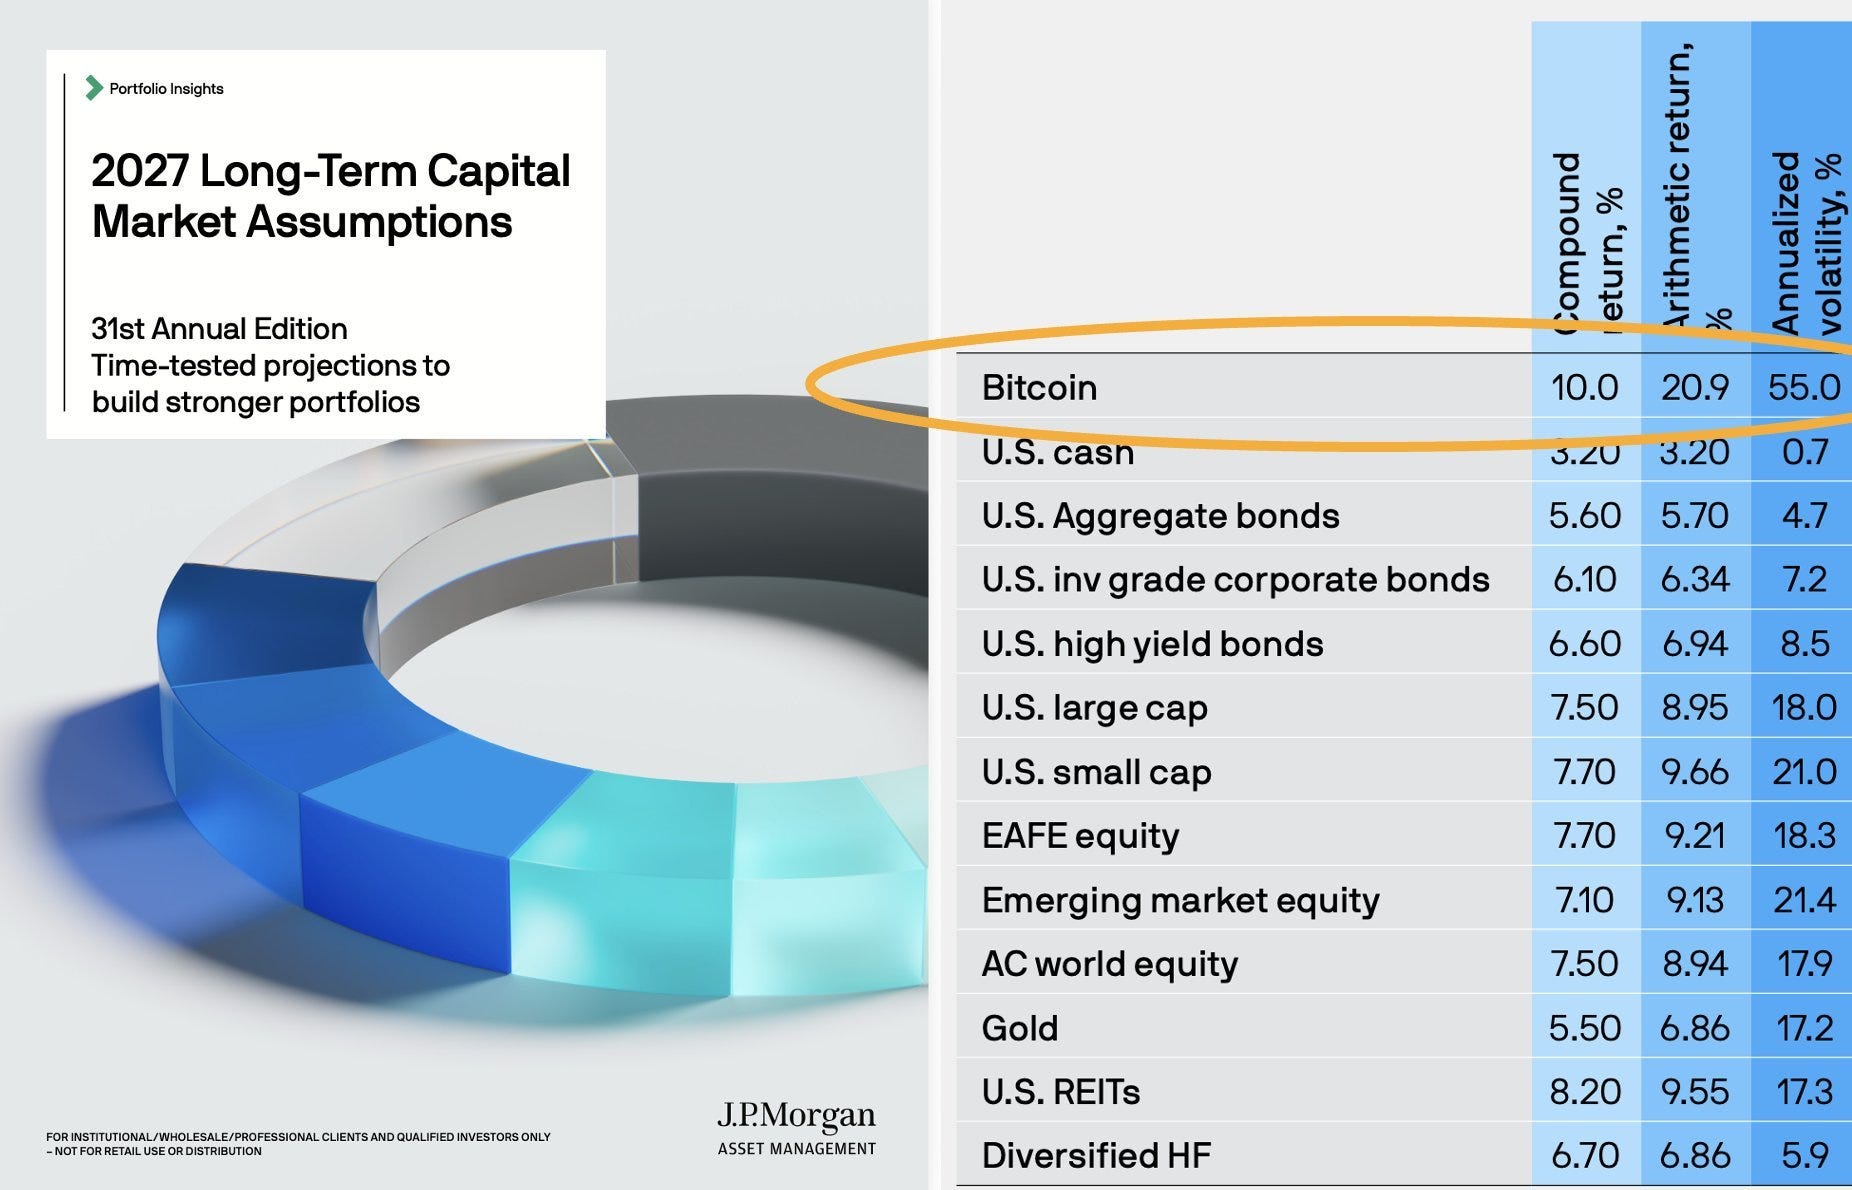
Over the last 6 months, BTC realized volatility is 30% vs +45% for many AI names. This is yet more evidence that the “Bitcoin is too risky” party is just wrong.
Perhaps some of the biggest news in the crypto world over the last week was Chamath (a prior BTC bull) suggesting “Bitcoin goes to zero” based on quantum computers breaking Bitcoin.
This is truly a question nobody knows the answer to right now but the worry is likely +15-20 years away at least and Bitcoin can upgrade to quantum-resistant technology as could everything else.
To put it into more perspective though, I think the near term worry is not with BTC. It’s with the general banking world.
Over the last 2-3 weeks we’ve seen increased headlines regarding cyber attacks and I think this is only the early stages of this. This alone should push banks towards cryptography and towards the blockchain which ends up being net bullish for crypto.
What’s Mispriced?
This is a section looking at the potential opportunities I’m seeing at the moment. I’ll split them by how I see the risk profile (high risk → low risk).
I’ll tend to aim for at least 3+ opportunities in every article I publish here…but that depends on what the market is offering at the time of writing.
You’ll also likely see overlap week to week. I am not a trader that changes his mind every few hours, days, or even weeks. If I see an opportunity, that opportunity sometimes stays around for weeks.
Last week we touched on:
Bloom Energy (BE) - Midsized position
Coinbase | COIN - Large position
Marvell (MRVL) - Small position
NuBank | NU (Medium Risk)
NU is a big position of mine. I was up ~20% on the trade but after today’s bloodbath in Brazil I’m back to my entry point…but most importantly with no current intention to sell.
A Bolsonaro win would have been a nice bullish catalyst for NuBank. But a Lula win is not necessarily bearish for NU.
Look at what NU has managed to do quarter after quarter over the last few years under Lula. Just last quarter we saw:
Net income of $1.1B (the first $1B+ quarter in its history), up 49% year-over-year FX-neutral.
Revenue up 39%.
140M+ customers.
Conditional approval for a US national bank charter expected in 2027.
Based on current growth, I think analyst forecasts of $1.13 in EPS in FY27 seems completely feasible (~27% growth on FY26) which means at $12.36 we’re trading at ~10.9x FY27 EPS (or 0.4x PEG). That’s too cheap in my opinion even given the macro risks.
On the other hand, the bear case is fair…but it’s no different to the bear case we had 12 months ago. A weaker real hurts the dollar value of earnings and higher rates raise funding costs. It’ll be more important for us to watch delinquencies over the coming quarters but again this news is nothing new.
Personally, I’m already exposed to Brazil via a large position in NU so I won’t be adding anymore here but I remain very happy to be holding for the time being.